Why a shortlist of factories is not the same as a supply base
The safety cushion you think you have
Procurement teams describe multi-sourcing the way engineers describe redundancy. You qualify two or three factories for the same part so that a fire at one does not stop the line. The assumption buried inside that plan is that the factories are independent. If they are not, the redundancy is decorative: one decision-maker, one cost base, one set of books, and one point of failure wearing several letterheads.
What a second source has to protect you from
Real multi-sourcing protects you against capacity failure, quality failure where a second source shares the same upstream supplier, and concentration risk where your supply base quietly becomes one company's order book. All three depend on one precondition, that the second source can behave differently from the first. If the same person prices both, it cannot tell you no.
Independence is a relationship, not a document
Two companies can have different names, registration numbers, shareholders and ultimate controllers and still be one supply base in everything that matters to you. They can share the person who signs, the person who books the payments, the trademark, and the same instinct about what your order is worth. When you ask four suppliers for a quote and get four answers from one management team, you are comparing price formatting, not competition.
A shortlist is a claim about independence, and a claim has to be checked. Whether one company is a real factory is a separate exercise, covered in how to verify a Chinese supplier is a real factory rather than a middleman.
What the registry tells you, and what it does not
Four layers of Chinese company identity
Chinese company data sits in four layers, and each answers a different question. Confusing them is the most common reason a supplier screen produces a false clean result. The table below sets out what each layer holds, what it can prove and what it cannot. The short version: the registered layer proves least, an algorithm-based screen usually lands on shareholding, the beneficial owner layer reaches the natural person at the top, and the people layer catches the links the other three miss.
The four fields worth pulling for every candidate
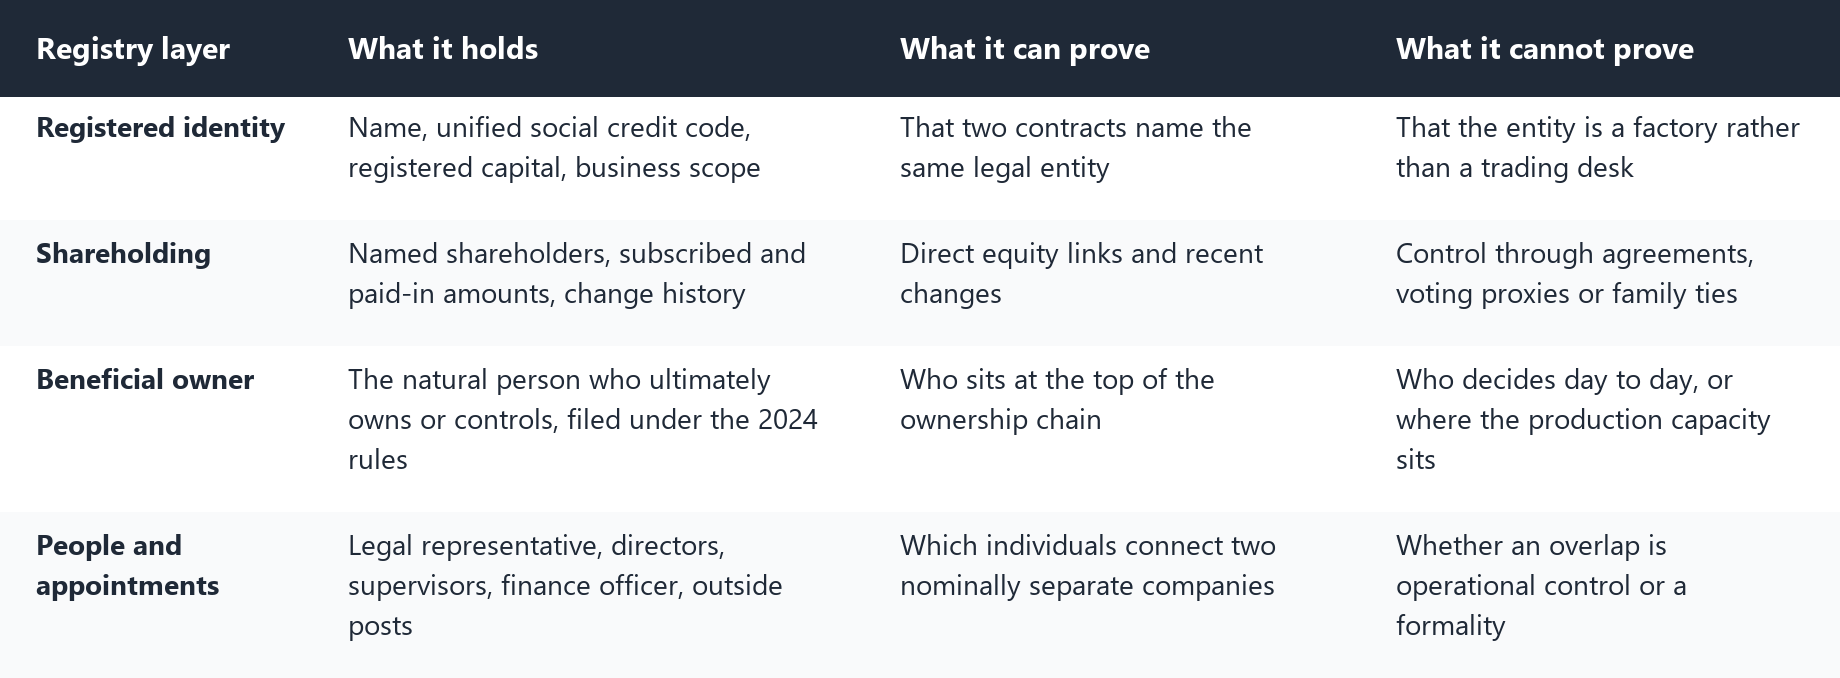
| Layer | What it holds | What it can prove | What it cannot prove |
|---|---|---|---|
| Registered identity | Name, unified social credit code, registered capital, business scope | That two contracts name the same legal entity | That the entity is a factory rather than a trading desk |
| Shareholding | Named shareholders, subscribed and paid-in amounts | Direct equity links and recent changes | Control through agreements, voting proxies or family ties |
| Beneficial owner | The natural person who ultimately owns or controls, filed under the 2024 rules | Who sits at the top of the ownership chain | Who decides day to day, or where the production capacity sits |
| People and appointments | Legal representative, directors, supervisors, finance officer, and outside posts they hold | Which individuals connect two nominally separate companies | Whether an overlap is operational control or a formality |
Read the last row first. Ownership structure changes slowly and is visible from the outside. Personnel overlap is what changes behaviour, and a quotation comparison will never expose it.
The three rules that define a beneficial owner
The beneficial owner rules, issued jointly by the People's Bank of China and the State Administration for Market Regulation, define a beneficial owner through any one of three tests. Direct or indirect ultimate ownership of more than 25% of the equity, shares or partnership interest. Failing that, ultimate enjoyment of more than 25% of the profit interest or voting rights. Failing that, actual control.
That third test is the one that matters to a buyer, and the rules set out what it means: deciding the appointment or removal of the legal representative, directors, supervisors or senior managers, deciding major operating or management decisions, deciding financial receipts and payments, or long-term actual control of important assets or the main funds. A company with five shareholders and no control agreement can still be controlled through its finance function.
The check that finds the link in minutes
Start with the trade name, not the company
The cheapest filter runs before any database. Take the Chinese names of your candidates and look at the first two characters, the trade name, rather than the whole registered name. If several companies share those characters and one of them is a trading company rather than a manufacturer, you have found the shape of the group before its name.
This works because Chinese trade names are chosen and groups reuse them. In our project the two candidate manufacturers shared no shareholders, no controller and no characters in their registered names, yet their trade names sat one character apart and both belonged to the same person who owned a third company outright.
Compare the four fields side by side
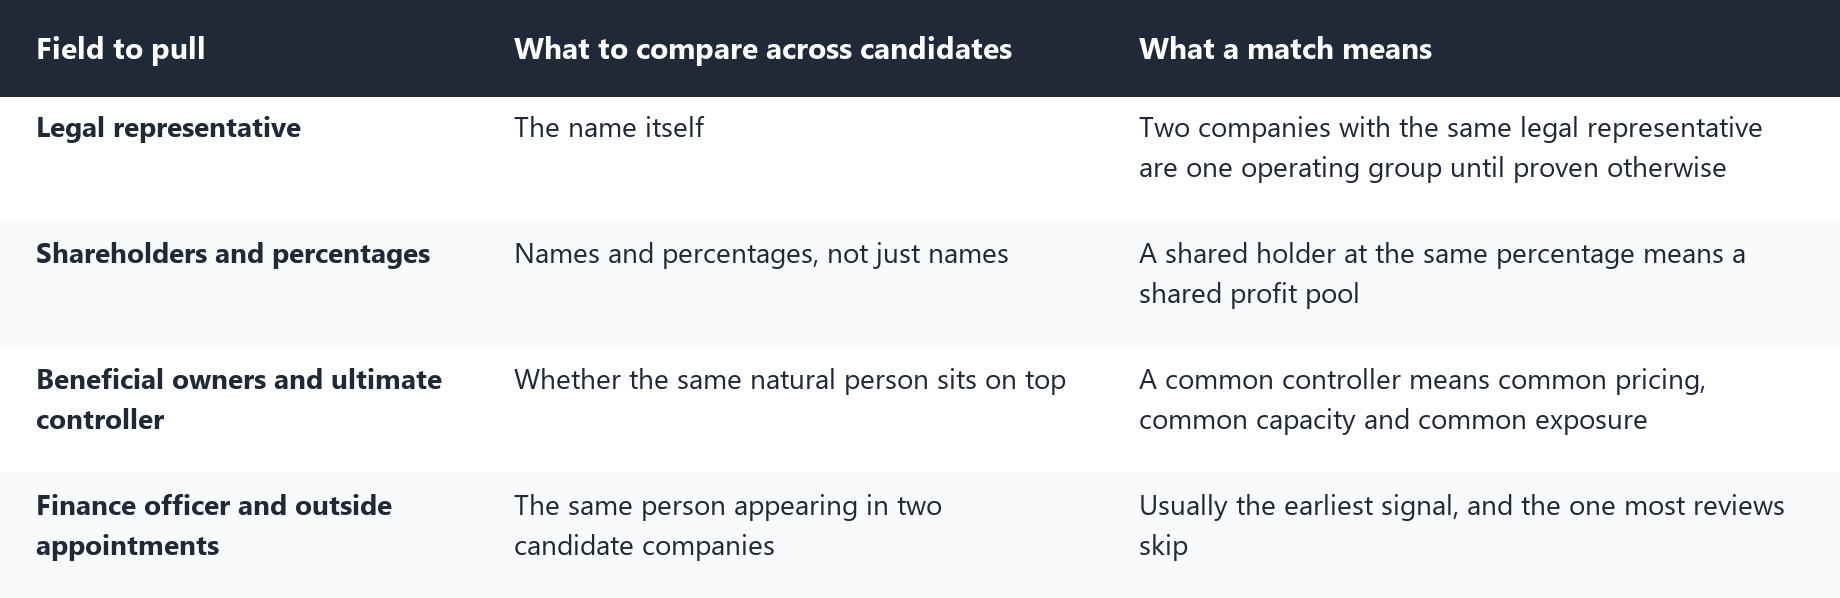
| Field to pull | Where it comes from | What to compare across candidates | What a match means |
|---|---|---|---|
| Legal representative | Registration record | The name itself | Two companies with the same legal representative are one operating group until proven otherwise |
| Shareholders and percentages | Shareholder record | Names and percentages, not just names | A shared holder at the same percentage means a shared profit pool |
| Beneficial owners and ultimate controller | Beneficial owner filing and penetration result | Whether the same natural person sits on top | A common controller means common pricing, common capacity and common exposure |
| Finance officer and outside appointments | Key personnel and outside appointment records | The same person appearing in two candidate companies | Usually the earliest signal, and the one most reviews skip |
Read the bottom row carefully, because the finance officer field behaves differently from the legal representative field. A legal representative is a public-facing and legally meaningful appointment. A finance officer is a back-office role that often sits with a family member or whoever controls the money. The same finance officer at two suppliers means one set of books.
Read the appointment list, not just the shareholder list
Every company has an internal list of who holds what role, and it is publicly visible: the legal representative, the directors, the supervisors, the finance officer, and then the outside appointments, meaning every other company where those people serve.
This last piece changed our view on the project. One individual sat as legal representative and director of one candidate, held a shareholding and the ultimate controller position in another, and served as finance officer of a third. The same individual also held roles in four further registered companies, one already deregistered. A shareholder screen would have shown two clean companies. The appointment list showed a network.
What we found on a glass bottle project
We were checking suppliers for a custom glass bottle programme. Two candidates came back from the initial screen looking textbook: a glass technology company in Jiangxi and a packaging products company in Guangzhou. Different names, registered capital, addresses, shareholders, and ultimate controllers. The two controllers were not the same person, which is exactly what a standard supplier verification checks, and would have passed both.
What linked them was a third name that appeared in neither shareholder list. One individual was legal representative and director of the Jiangxi company, held 50% of its equity with 50% of the voting rights, was the disclosed ultimate controller and a filed beneficial owner there, and was simultaneously recorded as finance officer of the Guangzhou packaging company. The same individual also held 100% of a separate technology company outright.
What the field comparison showed
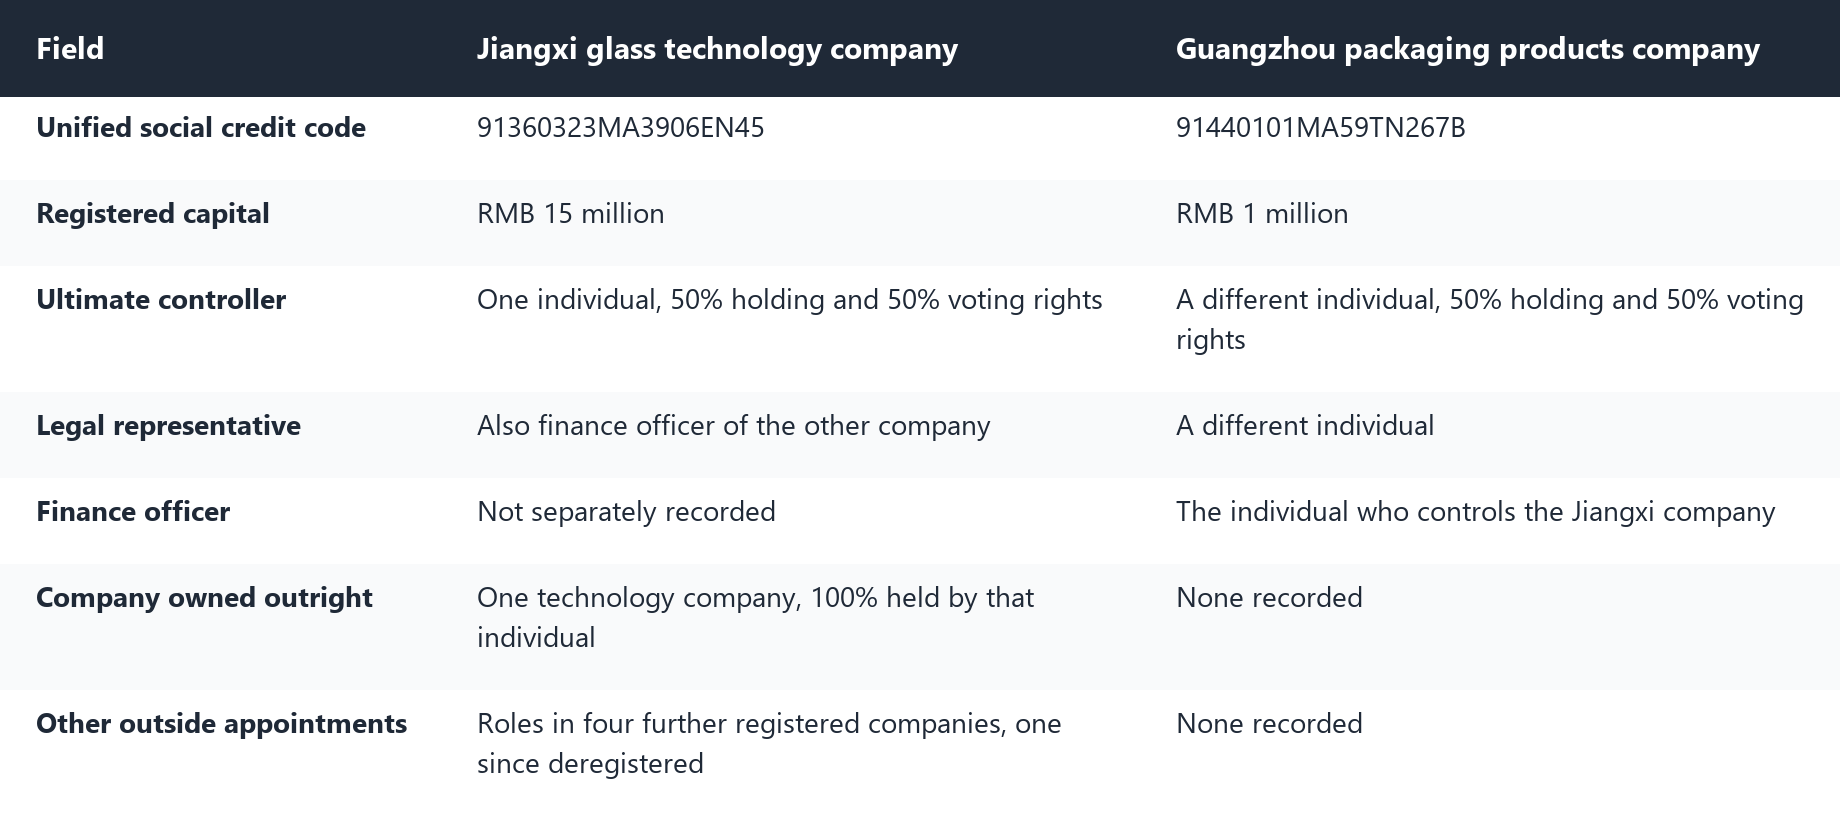
| Field | Jiangxi glass technology company | Guangzhou packaging products company |
|---|---|---|
| Unified social credit code | 91360323MA3906EN45 | 91440101MA59TN267B |
| Registered capital | RMB 15 million | RMB 1 million |
| Ultimate controller | One individual, 50% direct holding and 50% voting rights | A different individual, 50% direct holding and 50% voting rights |
| Legal representative | The individual who also serves as finance officer of the other company | A different individual |
| Finance officer | Not separately recorded | The individual who controls the Jiangxi company |
| Company owned outright | One technology company, 100% held by that individual | None recorded |
| Other outside appointments | Director or supervisor roles in four further registered companies, one since deregistered | None recorded |
Read the legal representative row and the finance officer row together and the structure appears. The person who legally runs the factory also runs the books of the trading company quoting alongside it, and separately owns the entity that owns the equipment. These are public registration records, we found no published evidence of wrongdoing, and we make no claim about one. The practical point is narrower: two quotations, one person.
What the registry could not tell us
The registry told us who owns what and who holds what role. It did not tell us who made the pricing decision, which company holds the moulds, or whether the two would have competed had we not looked.
We could not find published information on how the two companies divide production and sales work, because that division is not a filed fact. Whether the arrangement is a group structure, a family arrangement, a subcontracting relationship or three unrelated people who share a name cannot be determined from the filed records alone.
What the law gives you, and what it keeps from you
When one person running two companies becomes a liability problem
Company law is explicit that a shareholder who abuses the separate legal personality of a company and the limited liability of shareholders to escape debts and seriously harms creditors bears joint liability for the company's debts. More usefully for a buyer, the same article provides that where a shareholder uses two or more companies under their control to do this, each bears joint liability for the debts of any other.
Read that as an architecture, not a remedy. Whether an arrangement falls inside the article is a legal question that depends on facts neither the registry nor we can supply. The commercial lesson is simpler. If one person controls both sides of your shortlist, any price you negotiated against one was negotiated against both, and any plan that assumed you could switch volume between them assumed a capability that does not exist.
The database you will never be able to query
The beneficial owner rules create a central information management system at the People's Bank of China, and the filing information is pushed there by the registration system. Access is restricted. State organs may obtain it when performing their duties, and financial institutions and specific non-financial institutions may query it to meet their anti-money-laundering obligations. Everyone else is excluded, and a foreign buyer is in that category.
We could not find any provision that opens this system to overseas private buyers, and no published route for a foreign company to query it has been disclosed. What is publicly reachable is the registered and filed information the market regulator discloses, including the beneficial owner filing once made. The check is limited by what the company chose to file, not by what is true.
Why no filing found is not a clean result
There is an exemption, and it is wide enough to matter. A filing subject whose registered capital does not exceed 10 million yuan, whose shareholders or partners are all natural persons, and where no person other than those shareholders or partners actually controls or benefits from it, may undertake not to file beneficial owner information at all. Most small Chinese factories sit inside that exemption. We could not find any published figure showing how many filing subjects have used the undertaking rather than filed, and no public list of who has undertaken exists.
So the absence of a beneficial owner entry is not evidence of absence. The correct conclusion is that the public record is silent on that company, and silence is a finding you record, not a clearance you rely on. This is why our screen pulls the shareholders, the legal representative and the finance officer too: those fields are not exempt.
How we screen a shortlist now
Our sequence, and the order we do it in
We run four passes before we put a shortlist in front of a client, and the order matters more than the depth of any pass. First we pull, for every candidate, the unified social credit code, the registered capital, the business scope, the shareholders with percentages, the legal representative, the finance officer and the full list of outside appointments, and we put them in one table with a row per company and a column per field.
Then we read the table column by column rather than row by row, which is the opposite of how we used to read it. Row by row tells you about a company, column by column tells you about the group. A repeated legal representative, a repeated finance officer, a repeated shareholder, a repeated trade name, a shared address or a director who shows up three times are each a flag worth following. Third, we pull the outside appointments for every individual in the table, which is where the wider structure showed up in our project. Fourth, we weigh the comparison against the shape of the order: if two candidates share a controller or a finance officer we treat them as one source, we do not price them against each other, and we confirm in the contract who is producing, who is invoicing and who receives payment. Building a shortlist in a market where suppliers are plentiful is covered in how to shop a buyer's market of Chinese suppliers.
The question we ask after a hit
When the table produces a hit, we do not accuse anyone. We ask a factual question in writing, and we ask the same question of both sides. Which legal entity holds the production assets and which entity signs the contract? Which entity issues the invoice and which entity receives the payment? Are the two companies related, and if so how? What is the capacity of each if the order moves?
We ask both sides the same way because a supplier that answers openly is telling you something, and one that answers differently depending on which entity you asked is telling you more. The output of a hit is not a decision to drop a supplier. It is a decision to stop treating two entities as competing, to confirm where the capacity and the money sit, and to write that into the contract annex rather than a mental note.
Where a shared name is only a shared name
This method produces false positives, and we should say so plainly. Two companies can share a trade name because they are in unrelated lines of business. Two can share a finance officer because that person runs the accounting for a small cluster of clients, which is a real service model in China and not evidence of common control. Two can share a director because that person sits on a dozen small boards and does no day to day work at either.
Our rule is that a single overlap means investigate, and two or more independent overlaps across different layers mean treat as one until proven otherwise. When overlaps accumulate we change the commercial structure of the order. When they do not, we have learned something worth keeping. We cannot tell you from public records whether two Chinese companies are truly independent, but we can tell you whether they share a person, a shareholder, a name or an address, which is usually enough to decide whether your price comparison is real.
First published at chinagosource.com
Footnotes
1. People's Bank of China and State Administration for Market Regulation, Measures for the Administration of Beneficial Owner Information, Order No. 3 of 2024, in force 1 November 2024, Article 6 on the three beneficial ownership tests, Article 3 on the small scale undertaking exemption, Article 12 on restricted access to the central system, Article 10 on the 30 day change filing duty and Article 14 on the accuracy penalty: https://www.gov.cn/gongbao/2024/issue_11386/202406/content_6955755.html
2. Company Law of the People's Republic of China, revised 29 December 2023 and in force 1 July 2024, Article 23 on joint liability where a shareholder controls two or more companies, Article 40 on publicising subscribed and paid-in capital and equity change information, Article 56 on the shareholder roster and Article 57 on shareholders' right to inspect company records: https://www.gov.cn/yaowen/liebiao/202312/content_6923395.htm
3. State Council Regulation on the Registration of Market Entities, Order No. 746, in force 1 March 2022, Article 8 on registration items including the legal representative and shareholder names, and Article 9 on filing items which expressly include the beneficial owner information of companies and partnerships: https://www.gov.cn/zhengce/content/2021-08/24/content_5632964.htm
4. State Council Interim Regulation on the Publicity of Enterprise Information, Order No. 654, in force 1 October 2014 and amended 10 March 2024, Article 6 on publicising registration and filing information and Article 10 on publicising subscribed and paid-in capital and equity transfer information within 20 working days: https://www.gov.cn/zhengce/content/2014-08/23/content_9038.htm
5. Shanghai Municipal Development and Reform Commission register of company registration rules and beneficial owner filing procedures, confirming that beneficial owner information sits inside the public registration and filing regime rather than inside a closed database: https://fgw.sh.gov.cn/ys-sczr-2.4.2.1/